
Every time a client pays your studio by card, a slice of the payment goes to the processor and the card networks, not to you. For most online card payments that slice is a percentage plus a fixed amount per transaction, and your client never sees it. The way to keep it from eating your margin is to decide in advance who absorbs it: build it into your rates, pass it on through a clearly disclosed surcharge where your state allows it, or move large payments to lower-cost methods. Then write that decision into your payment terms so nobody is surprised at the final invoice.
This guide is for mixing and mastering engineers, podcast producers, post-production facilities and studio owners who take deposits, session fees and revision payments by card.
TL;DR
- Card fees are charged to you, the merchant. Your client pays the invoice amount and sees no fee line unless you add one.
- Stripe’s published online rate for standard U.S. cards is 2.9% plus 30 cents per successful charge. Other processors price differently, and rates change, so check your own statement.
- A flat fee hurts small payments most. A $50 revision payment loses a bigger share than a $2,000 album mix.
- You have three options: absorb the fee in your rates, add a disclosed surcharge where it is legal, or steer big payments to bank transfer or ACH.
- Whatever you choose, put it in your written payment terms and on the quote, before work starts.
Table of Contents
- What a card payment actually costs a studio
- Who pays the fee: you, unless you plan otherwise
- Match the option to the kind of work
- The fees you forget: disputes and failed payments
- Put it in writing: the payment policy
- Get paid faster, so fees cost less than delays
- Where the fee meets your workflow
- Try Audome for studio payments
- Perspective
- Checklist: reducing the cost of card fees
- FAQ
- Sources
What a card payment actually costs a studio
A card payment passes through several parties. The client’s bank (the issuer) takes a fee called interchange. The card network, such as Visa or Mastercard, takes a smaller assessment. Your payment processor adds its own markup. The total is what you see deducted from your payout.
If you use a modern all-in-one processor, you rarely see those three layers separately. You see one rate. Stripe, for example, publishes a single standard rate for domestic online card payments: 2.9% plus 30 cents per successful charge. Check the page for the current figure and for extra charges such as international cards, currency conversion or disputes, because those can change.
A quick way to see what that means for a studio:
| Payment | Fee at 2.9% + $0.30 | Share of payment lost |
|---|---|---|
| $50 paid revision | $1.75 | 3.5% |
| $250 podcast episode edit | $7.55 | 3.0% |
| $600 single-song mix | $17.70 | 3.0% |
| $2,000 album mastering | $58.30 | 2.9% |
| $5,000 post-production package | $145.30 | 2.9% |
The arithmetic is the percentage of the payment plus 30 cents. Your own rate may differ, so replace the percentage with the one on your agreement.
Two things stand out. First, on a normal job the fee is roughly three cents on the dollar, which is real money across a year but not ruinous. Second, the fixed 30 cents bites hardest on small payments, which matters if you sell paid revisions, rush fees or stem requests.

What a year of card fees looks like
Take a mixing engineer who invoices $60,000 a year and collects 80% of it by card. That is $48,000 in card payments. At roughly 3%, the fees come to about $1,440 a year. For a small studio billing $200,000 with most of it on cards, the same math gives about $5,000 or more. That is the cost of a part-time assistant for a month or the price of a good preamp pair, so it deserves a decision rather than a shrug.

Who pays the fee: you, unless you plan otherwise
A common worry is that the client will see an ugly fee on their receipt. They will not. The processor deducts its charge from what you receive, so a client who pays $300 pays $300. You receive slightly less.
That means the fee is a cost of doing business, like software or rent. The question is where you recover it. Studios usually choose one of three approaches.
Option 1: build it into your rates
The simplest approach is to price with the fee in mind. If your target take-home on a mix is $500 and you expect to lose about 3% to card fees, quote $515 or round up to $525. The client sees one price and no extra lines.
This works well for flat-rate packages (per song, per episode, per album). It keeps invoices clean and avoids any legal questions about surcharging. The downside is that clients who pay by bank transfer subsidize clients who pay by card, which is usually acceptable.
Option 2: add a disclosed surcharge
A surcharge is a separate fee you add when a client chooses to pay by card. Surcharging is regulated, and the rules come from two places: card network rules and state law. In broad terms:
- Card network rules cap the amount of a surcharge and require that you tell customers before they pay.
- Some states restrict or ban credit card surcharges, and some limit how they can be shown.
- Surcharges generally apply to credit cards, not debit cards.
- The surcharge should reflect your actual cost of accepting cards, not become a profit line.
Because the details differ by state and by processor, confirm the current rules with your processor and your state attorney general or a business attorney before adding a surcharge. Your processor’s help pages will also tell you how to register to surcharge, since networks typically want advance notice.
Also consider how it feels. A line reading “card processing fee” on a $1,200 mix invoice can irritate a long-term client. A discount for paying by bank transfer, often described as a cash or ACH discount, usually lands better, since it reads as a reward rather than a penalty. Check state rules on that as well.
Option 3: move large payments off cards
For big jobs, such as a $5,000 album package, you can offer bank transfer (ACH) as the preferred method. ACH payments typically cost far less than cards. You can still accept cards for deposits, small fees and clients who prefer them.
This is a good fit for repeat label and agency clients, who often pay by ACH anyway because their accounting teams prefer it.
Match the option to the kind of work
Not every payment deserves the same treatment. Here is a practical way to split things up.
| Type of payment | Typical size | Best approach |
|---|---|---|
| Deposit or booking fee | $100 to $500 | Accept cards, absorb the fee in your rate |
| Paid revision or rush fee | $25 to $150 | Card, priced to include the fixed fee |
| Per-song or per-episode job | $150 to $1,000 | Card or ACH, fee built into the rate |
| Album, series or post package | $2,000 and up | Offer ACH first, accept cards as a backup |
| Stored-file retrieval | $25 to $100 | Card at checkout, fee built in |
The lowest-value payments are where a fixed per-transaction fee is a larger share. If you charge $20 for an extra revision and lose $0.88 to the fee, that is 4.4%. Pricing a revision at $25 instead of $20 fixes the gap without anyone noticing.
The fees you forget: disputes and failed payments
Percentage fees are only part of the picture. Two other costs catch studios out.
Chargebacks. If a client disputes a card charge, the bank can pull the money back while the dispute is reviewed, and processors typically charge a dispute fee on top. Studios are exposed because the product is intangible: a client who has downloaded the final master can still claim the service was not delivered. Strong records are your defense: a signed agreement, a written approval of the mix, and a log showing the client heard and approved the work.
Payment after delivery. Handing over final files before payment clears is the most common way studios end up chasing money, and chasing money costs hours. The cleaner approach is to hold final downloads until payment is confirmed. We cover that in detail in our guide to locking final files until paid, and the logic for contracts is in approval before download.
Put it in writing: the payment policy
Card fees only become an argument when clients learn about them late. A short, clear payment policy removes the argument. Include:
- Accepted methods. Card, ACH, wire. State which you prefer for large jobs.
- Who covers fees. Either “our rates include payment processing” or a clear surcharge amount, stated before the quote is accepted.
- Deposit terms. How much, when due, and whether it is refundable. Our post on deposit policy and refund windows walks through what to specify.
- Revision rules. How many rounds are included and what extra rounds cost.
- Release of files. Final files are delivered once payment clears.
We have a longer walk-through with a template in our studio payment policy guide. If you are setting up a new client intake process at the same time, client onboarding for audio studios shows where the payment terms fit in the sequence.
Get paid faster, so fees cost less than delays
A card fee of 3% looks small next to the cost of a late invoice. A mix that sits unpaid for 45 days ties up cash, and each reminder email costs you time. Studios that put a payment link right in the invoice tend to see clients settle sooner, because paying takes one click instead of a login. The approach is laid out in our piece on embedding pay links in invoices.
That is why the fee question belongs next to the cash flow question. If a card payment arrives in two or three days and saves you three rounds of follow-up emails, the 3% buys you something real.
Where the fee meets your workflow
Most studios handle money in one place, files in another and feedback in a third. That split creates the problems above: the client downloads before paying, revision rounds sprawl past what was agreed, and the card charge for extra work has to be arranged by hand.
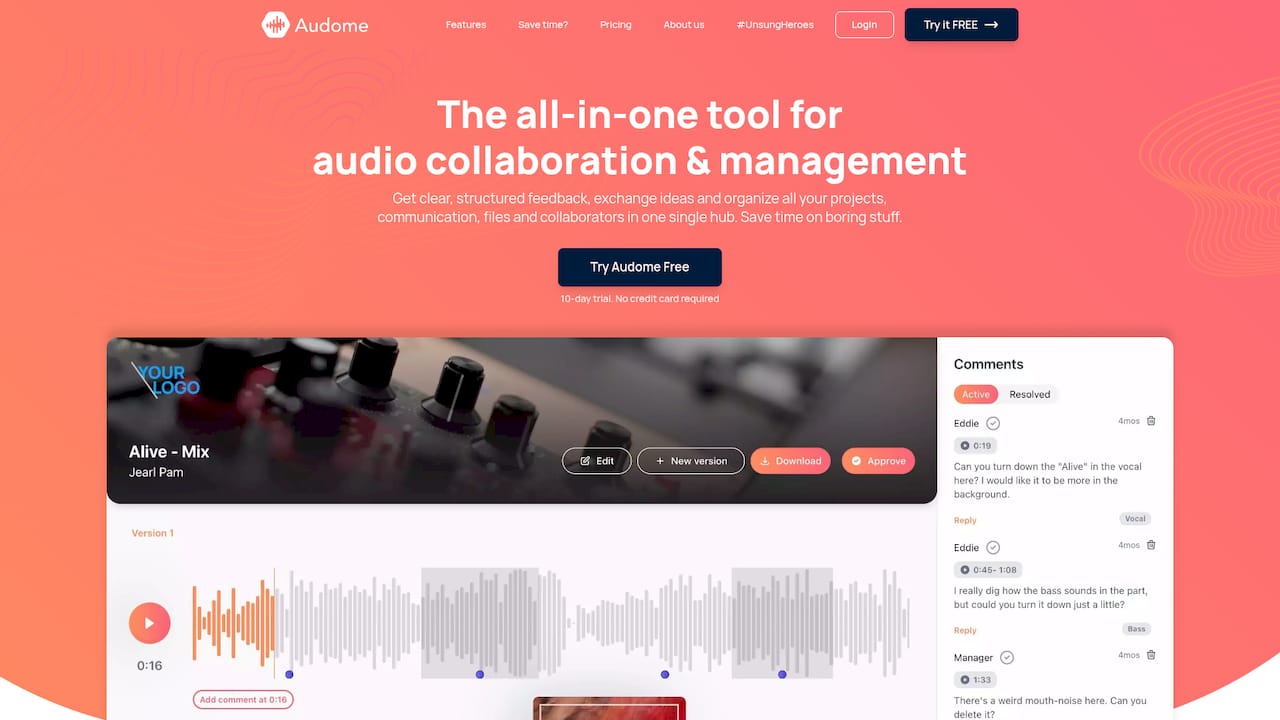
Audome is built to put those pieces together. It integrates with Stripe for payments, lets you set revision limits and bill for paid revisions, and offers download controls so final files can stay locked until the work is settled. Clients can listen, comment on the waveform with time-stamped notes and approve without logging in, through a password-protected, branded portal. The payment step sits inside the same place where the client approves the mix.
For a studio that sells paid revisions, this matters for the fee math too. A paid revision is exactly the small, fixed-fee-sensitive payment described above, and having the price and the charge attached to the revision request means you set it once, at a level that already covers the processing cost.
Try Audome for studio payments
Audome is a subscription tool for studios and audio professionals, with a free trial first. The Studio plan is $12.50 per month or $150 per year, and the Pro plan is $48 per month or $576 per year. Full details are on the Audome pricing page, and you can see how the whole workflow fits together on the Audome home page.
Payment processing rates are set by the processor you connect, so check its published pricing for the current figures.
Perspective
Studios talk about card fees as if they were a tax. They are not. They are a cost you can plan around, and the studios that handle them best treat them as part of the quote, not a surprise at the end.
We built Audome around a simple idea: the moment a client approves a mix is the moment you should be able to get paid, without a second system and without chasing. When files, feedback, revisions and payment live in one place, you set your revision limits and your price once, and the client sees a clear path from approval to download.
The no-login portal matters here more than people expect. A client who can open a link, hear the mix in full quality, leave a note at the exact second that bothers them and pay in the same visit is a client who pays on time. A 3% fee is a small price for that. A 45-day wait is not.
Our advice: decide who covers the fee, write it down, price your small payments with the fixed fee in mind, and hold final files until payment clears.
Kreg
Checklist: reducing the cost of card fees
- Look at your last three months of processor statements and add up the total fees.
- Divide fees by card volume to get your real effective rate.
- Raise prices on small payments (revisions, rush fees) so the fixed per-transaction fee is covered.
- Offer ACH for jobs above a size you choose, and mention it on the quote.
- Decide on surcharging only after confirming your state’s rules and your processor’s requirements.
- Add a line to your payment policy on who covers processing costs.
- Keep approval records for every job, to be ready if a dispute arrives.
FAQ
Do my clients see the credit card fees?
No. The processor takes its fee out of your payout, so a client who pays a $400 invoice pays $400. They only see a fee if you add a separate surcharge or processing line yourself. If you do, disclose it before they agree to the quote.
How much will card fees cost my studio per year?
A useful estimate is about 3% of whatever you collect by card, since common online rates are a percentage plus a fixed amount. Stripe’s standard U.S. rate is 2.9% plus 30 cents per charge, for example. On $50,000 in card payments that comes to roughly $1,500 to $1,600, depending on how many transactions there are. Your own statements give the exact figure.
Can I charge clients extra for paying by card?
In many U.S. states you can, within limits set by card network rules and state law, and some states restrict or prohibit it. You generally need to disclose the fee before payment and keep it tied to your actual processing cost. Confirm the rules for your state with your processor or a business attorney before you add one.
Is it better to absorb the fee or pass it on?
For most studios, building it into the rate is simplest and keeps client relationships smooth. Offering a lower price for bank transfer on large jobs is a good middle ground. A visible surcharge works best with clients who already expect it and where it is clearly allowed.
How do I stop clients disputing a card payment?
Keep a signed agreement, written approval of the final mix and a record of revisions. Hold final files until payment clears, and state your deposit and revision terms up front. Clear records are the strongest evidence if a bank reviews a dispute.