
A late payment policy sets clear payment deadlines and consequences. Start by adding one concise, contract-backed due date and fee trigger to every contract and every invoice you send. That single step protects your cash flow and gives you an enforceable standard instead of an awkward guessing game every time a payment slips.
TL;DR:
- A late payment policy should specify a clear due date, acceptable payment methods, and the exact moment funds are considered on time, such as when they clear bank processing.
- The escalation timeline typically starts with reminders before the due date and includes late fees, personal outreach, service restrictions, and possible collection attempts if overdue.
- Enforcing late fees requires prior written agreement in the contract, adherence to state laws, and a cap on fees to remain lawful and fair.
- Automating routine reminders and integrating pay links in invoices shortens payment cycles, but human judgment is needed for exceptions and disputes.
- Consistent communication and early disclosure of policies help maintain client trust and reduce friction from late payments.
Table of Contents
- What every late payment policy needs to include
- Setting late fees: flat rate, percentage, or both
- Building an escalation timeline that clients can predict
- Talking to customers about the policy before it becomes a problem
- Automating the policy without losing the human touch
- Staying inside the legal lines on fees and enforcement
- Three clause templates you can copy into a contract today
- Dealing with clients who are late again and again
- How late payments quietly damage client relationships
- How to negotiate net terms that actually fit your business
- What a late payment policy does for your cash flow
- Why policy alone isn’t enough
- Turning your policy into an automatic paywall
- Sources
- FAQ
What every late payment policy needs to include
A policy only works if it answers the questions a client will ask before they ask them. That means naming the due date, the accepted payment methods, and what happens the moment a payment is late.
Start with the due date itself. Decide whether “net 30” means 30 calendar days or 30 business days, and say so explicitly. Calendar days are easier to track and more common, but business days give you a buffer around weekends and holidays if you invoice manually.
Next, define receipt. A payment is not “on time” because the client clicked submit. It is on time when funds clear, so specify that in writing to avoid disputes over bank processing delays.
The policy should live in three places at minimum:
- The contract or proposal, where the client agrees to terms before work starts.
- Every invoice footer, so the due date and fee terms are visible at the point of payment.
- Onboarding materials or a welcome email, so nothing about the terms feels like a surprise later.
Also document who owns the invoice and how disputes get raised. A short dispute window, such as five business days from invoice date, keeps clients from contesting charges months after the fact while still giving them a fair chance to flag genuine errors.
Setting late fees: flat rate, percentage, or both
Most businesses choose between a flat fee and a percentage-based finance charge, and the right answer depends on your invoice sizes. A flat fee is simple to apply and easy for clients to understand, but it can feel trivial on large invoices and punitive on small ones.
A percentage charge scales more fairly. On a $500 invoice, that same rate produces $7.50, which keeps the penalty proportional to the amount owed.

Businesses commonly apply a flat fee or a percentage finance charge, often in the 1 to 2% monthly range, though the exact figure depends on your contract terms and the laws governing your business. There is no single lawful rate everywhere, so review your state’s rules before locking in a number.
A few practical rules of thumb:
- Use simple interest, not compounding. Compounding late fees on top of late fees grows fast and invites disputes, while simple interest stays predictable and easier to defend.
- Set a cap so the fee never exceeds a fixed percentage of the invoice, which protects you from appearing punitive.
- Include a short grace period, often three to five days, before the fee triggers.
- Add an effective date so clients on older contracts aren’t blind sided by new terms.
Building an escalation timeline that clients can predict
An escalation timeline turns a vague policy into a process your team can run without guesswork. Publish the sequence so clients know exactly what happens and when.
- Day 0: Invoice sent with due date and fee terms visible.
- Day minus 3: Automated courtesy reminder before the due date.
- Day 1 to 5: Grace period; a friendly nudge if payment hasn’t posted.
- Day 6: First overdue notice and late fee assessment.
- Day 15: Personal outreach from a team member, not a bot.
- Day 30: Service restriction, such as pausing new deliverables or holding final files.
- Day 60+: Referral to collections or legal counsel as a last resort.
Pause the clock when a client raises a genuine dispute or hardship request. Ask them to identify the specific line item and provide supporting detail within a short window, often five business days, so the undisputed portion of the balance stays collectible while the disputed part gets resolved separately.
Pro Tip: Hold final deliverables, not work in progress. Clients respond faster to “your finished files are ready once payment posts” than to a stalled project they can’t see progress on.
Enforcement doesn’t have to mean burning the relationship down. Structured payment plans, temporary service restriction, or a hold on final files all give a client a path back into good standing without an immediate shutdown.

Talking to customers about the policy before it becomes a problem
The best late payment policy is the one a client never has to be surprised by. Disclose it early and repeat it often.
- Put a one-line summary in the contract or proposal: “Invoices are due within 30 days; unpaid balances after that incur a 1.5% monthly fee.”
- Repeat the same line in the invoice footer, matched word for word so nothing looks inconsistent.
- Mention it once in an onboarding email, framed as standard practice rather than a warning.
For reminders, keep the tone plain. A pre-due reminder might read: “Just a heads up, invoice #1042 for $1,200 is due Friday.” A first overdue notice can stay just as calm: “Invoice #1042 is now five days past due. A $25 late fee applies as of today per our agreement.”
If a call becomes necessary, two short scripts cover most situations. For a polite reminder: “I wanted to check in on invoice #1042, it looks like it’s a few days past due, is everything okay on your end?” For escalation: “We haven’t received payment on invoice #1042, and per our agreement a late fee now applies. Can we set up a plan to close this out this week?”
Automating the policy without losing the human touch
A written policy only works if someone, or something, tracks it. Centralize every invoice’s status in one system so you always know what’s outstanding, what’s overdue, and what’s already triggered a fee.
Automate the routine parts: due-date reminders, overdue notices, and fee calculations should fire without anyone remembering to do it manually, leveraging a CRM & Messaging Platform For Local Businesses – Reviews to streamline invoice reminders. Route the exceptions, disputes, hardship requests, and strategic accounts, to a human who can make a judgment call.
- Embed a pay link directly in the invoice so clients can settle in one click instead of hunting for a bank portal.
- Consider requiring payment before final deliverables unlock, especially for project-based work where the finished file is the leverage point.
- Track days sales outstanding (DSO) as your core cash-flow health metric.
- Watch the percent of invoices overdue and the average amount overdue monthly to catch drift before it becomes a crisis.
Embedding pay links directly in invoices tends to shorten the time between invoice and payment, since clients settle in the same window they’re already reviewing the bill instead of adding a second step later.
Staying inside the legal lines on fees and enforcement
Enforceability starts before the invoice, not after it. A late fee only holds up if the client agreed to it in writing before the work began, so retroactive fees added to an already-overdue invoice are on shaky ground.
- Disclose the fee structure in the signed contract, not just the invoice.
- Check your state’s usury or consumer protection rules, since some states cap the percentage a business can charge on overdue consumer balances.
- When in doubt, choose a reasonable rate and a cap rather than the maximum you think you can get away with.
- Keep the FTC’s warnings about hidden or late-disclosed fees in mind: undisclosed charges invite complaints and regulatory scrutiny even when the underlying fee is modest.
One common confusion is worth clearing up directly. The Prompt Payment Act governs federal procurement contracts, where interest penalties on late government payments start the day after the required payment date and follow a specific federal calculation method. It does not apply to private business-to-business agreements, though its structure, a clear trigger date and a defined interest calculation, is a reasonable model to borrow when building your own internal formula.
Three clause templates you can copy into a contract today
You don’t need a lawyer to draft a first version of these clauses, though it’s worth having one review the final language, especially if your rate or structure is unusual.
Net terms with percentage fee:
“Payment is due within [30] days of invoice date. Balances unpaid after the due date incur a [1.5]% monthly finance charge, capped at [15]% of the invoice total.”
Flat fee with grace period:
“A grace period of [5] days follows the due date. Payments received after the grace period incur a flat late fee of [$50] per invoice.”
Escalation and collections:
“Accounts more than [30] days overdue may have new work paused and final deliverables held until balance is paid in full. Accounts more than [60] days overdue may be referred to collections.”
Place the first two in your proposal and main contract, and repeat a short version in the invoice footer. Keep the escalation clause in the master contract only, since it rarely needs to appear on a routine invoice.
Dealing with clients who are late again and again
A single late payment is a cash-flow hiccup. A client who is late three invoices in a row is a different problem, and your policy should treat it that way.
Track repeat lateness by client, not just by invoice. Once someone crosses a threshold, such as two late payments in a rolling six-month period, move them onto stricter terms automatically: shorter net terms, a deposit requirement, or payment due before final files release rather than after.
Have a direct conversation before the third late payment, not after. Something like, “We’ve noticed the last two invoices ran past due, so going forward we’ll need payment before we deliver final files,” sets a boundary without accusation.
For genuinely repeat offenders, consider requiring a deposit upfront on future projects or moving them to pay-per-milestone billing instead of a single invoice at the end. This protects your cash flow while still leaving room for the relationship to continue if the client corrects course.
How late payments quietly damage client relationships
Late payments cost more than the cash you’re waiting on. They create friction in a relationship that otherwise runs smoothly, and that friction tends to show up in places you don’t expect, like slower approvals, more revision requests, or a client who becomes harder to reach once money is owed.
A clear, consistently enforced policy actually protects the relationship rather than threatening it. Clients generally respect a business that treats payment terms as a normal part of professionalism, the same way they’d expect a clear scope of work. What damages trust is inconsistency: charging one client a late fee and waiving it for another, or going quiet on enforcement until frustration boils over into a terminated contract.
Enforcing terms evenly, and communicating early rather than after a deadline has already passed, keeps the commercial relationship separate from the creative or working relationship. That separation is often what determines whether a client stays for the next project.
How to negotiate net terms that actually fit your business
Net terms should match your delivery risk and your own cash position, not just what a client asks for. A client requesting net 60 is really asking you to finance their project for two extra months, and that’s a real cost even if no interest changes hands.
When a client pushes for longer terms, counter with a structure instead of a flat no. Offer net 30 with a small early-payment discount, or net 45 with a deposit upfront to offset the delay. Longer payment terms tend to correlate with a higher risk of cash-flow strain, which is a reasonable thing to say plainly when you’re explaining why you’re not offering net 90 to a new client.
New clients generally warrant shorter terms and a deposit until they’ve built a payment history with you. Established clients with a clean track record have earned the flexibility of longer terms or fewer upfront requirements. Put the logic in writing internally so your team applies it consistently instead of case by case.
What a late payment policy does for your cash flow
A late payment policy is a cash-flow tool before it’s a legal one. Every invoice sitting unpaid past its due date is working capital you do not have access to, and the effect compounds across a client roster.
More than half of small businesses report being owed money from unpaid invoices at any given time, per Intuit QuickBooks, which underscores why a written, consistently enforced policy matters more than most owners assume. A policy with a clear due date, a real fee trigger, and a predictable escalation path shortens the average time an invoice sits unpaid, which directly improves the cash you have on hand to cover payroll, materials, or your own bills.
The businesses that struggle most with this usually don’t lack a policy on paper. They lack consistency in applying it, which trains clients to treat your due dates as optional.
Why policy alone isn’t enough
Writing a policy is the easy part. The harder part is building a workflow where the policy enforces itself instead of relying on someone remembering to chase a payment. In studio and creative work specifically, unpaid final deliveries and endless “just one more round” revision requests are the two places policies quietly fail, because the leverage point, the finished file, gets handed over before the money does. Pairing clear terms with a payment gate on final downloads and a cap on free revisions closes both gaps at once.
— Kreg
Turning your policy into an automatic paywall
A written policy tells clients what should happen. Some collaboration platforms can require payment through integrated payment processing before a client can download final files, so the deliverable itself becomes the enforcement mechanism instead of a follow-up email.
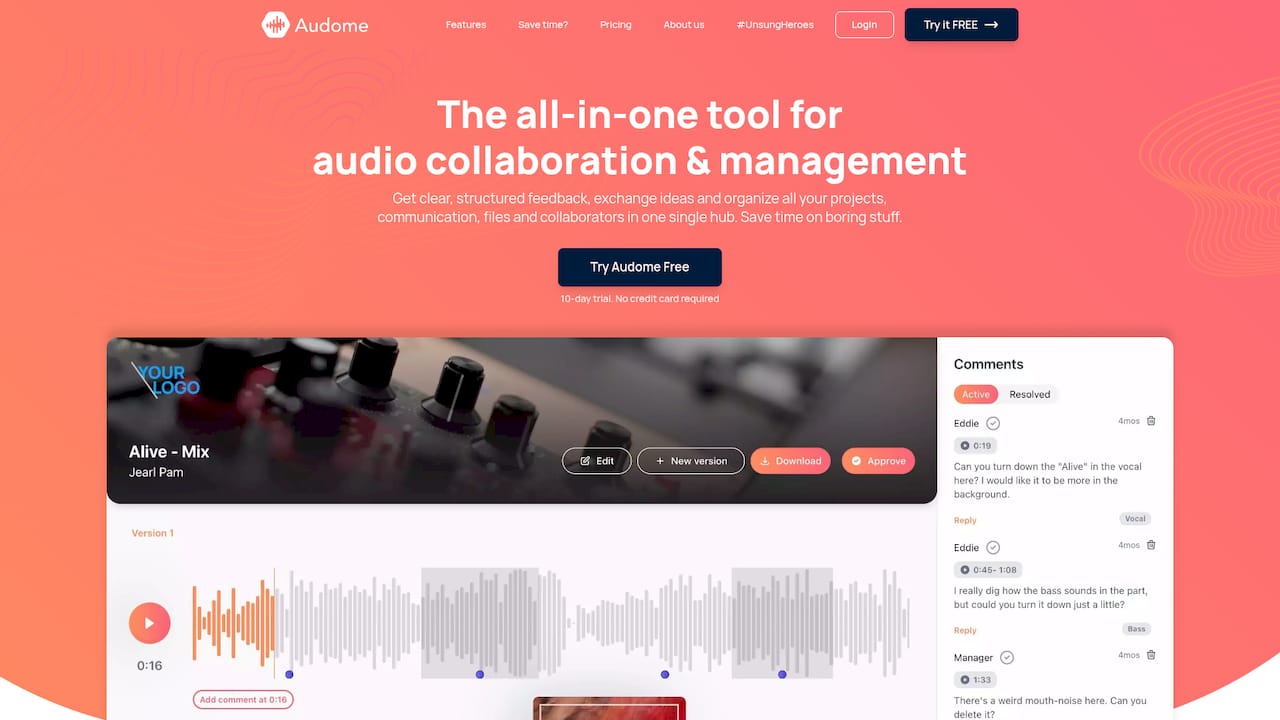
Some platforms allow capping the number of free revisions on a project and automatically charging for extras once a client goes past that limit, which helps manage endless revisions that late payment policies alone don’t solve. Revision requests can be attached to timestamped feedback on audio waveforms to reduce ambiguity about what was requested and when. Check current plans and pricing on the Audome pricing page to see which tier fits your studio.
Sources
- Late fees explained | Stripe
- Chapter 5000 Prompt Payment Act (PPA) Guidance | TFX
- Notice of Proposed Rulemaking: Unfair or Deceptive Fees | FTC
FAQ
How many days late can a payment be before action is required?
Most policies define lateness starting the day after the due date, with a short grace period of three to five days before a fee applies. Beyond that, action typically escalates on a set schedule, such as a notice at day 6 and a fee assessment shortly after, based on the terms in your contract.
Will a payment being a few days late affect your credit?
A payment that is only a few days late generally does not get reported to credit bureaus, since most creditors report only after 30 days past due. Business-to-business late fees under a private contract are a separate matter and don’t typically involve credit reporting at all.
Can you have a strong credit score with some late payments on record?
A strong credit score with occasional late payments is possible, since scoring models weigh payment history over time rather than penalizing a single incident permanently. Recent and severe lateness (30, 60, or 90 days past due) affects scores more than an isolated minor delay.
How long do you have to pay a late fee once it’s assessed?
That depends entirely on the terms in your contract or invoice, since there’s no universal deadline for paying an assessed late fee. Most policies expect the fee paid along with the original balance, and the outstanding amount continues accruing under the same terms until it’s settled in full.